
Building personal wealth outside the company
Planning savings and investments outside your business, so your finances do not depend on it alone.
Plan your personal finances alongside your business: pensions, investments, family protection and life after a sale. Start by finding an adviser who understands how your income, company and longer-term plans fit together.
The adviser does not need to be an expert in every corporate issue. They do need to understand where personal financial planning connects with the business.
Planning savings and investments outside your business, so your finances do not depend on it alone.
Thinking about the personal financial consequences of a business exit before the money arrives.
Understanding how pensions and other assets fit alongside the value locked inside the company.
Considering what happens to the family or business if a key person cannot work or dies.
A financial adviser can help you plan what your money needs to do for you. A sale, restructuring or tax return can also require an accountant, solicitor or corporate-finance specialist. Agree who is responsible for each part before paying for the work.
Personal cash-flow planning, pensions, investments and protection. Ask how they would test your retirement plans if the sale price or completion date changes.
The tax consequences of taking money from the business, pension contributions and a potential sale. Your business structure and the terms of a transaction affect the work needed.
Legal documents, ownership and transaction terms. Ask who coordinates with your personal adviser, and what information they need permission to exchange.
For example, an expected sale price is not the same as the amount available to invest. First establish the ownership, deal costs, tax and timing with the relevant professionals. Then ask an adviser to build a personal plan around the proceeds you expect to receive.
Start with planning before a business sale, decisions after a sale or where financial advice and tax advice overlap.
Regular exposure can matter more than a generic “business owner” label on a profile.
Ask about complexity, minimum assets and whether they work with founders before and after exits.
Get the actual pounds, not just the percentage.
For business-owner planning, coordination with accountants, solicitors or corporate-finance advisers can be relevant.
The help you need before selling your business may differ from what you need once you receive the money.
Ask for a written quote that separates the plan, implementation and ongoing support. Our published-fee research shows how firms describe these charges. More complex work may need a separate quote.
This is an example, not a quote. An adviser may charge a fixed fee, use different rates for different amounts or set a maximum charge.
Use the fee calculatorStart with our local guides. Consider looking further afield if you need experience that is harder to find nearby.
The useful starting point is what the change means for your own income, family and retirement. Agree which figures your accountant or sale team must confirm before an adviser builds the plan. Give each firm the same brief and ask it to separate a financial plan, investment recommendations and ongoing management in its quote.
| Your situation | The question to resolve | Useful output from the work |
|---|---|---|
| Income varies with the business | What personal spending must be covered if drawings or dividends fall? | A household cash-flow plan with clearly stated income assumptions. |
| A sale is being discussed | What money is expected, when will it arrive and which costs or tax amounts remain estimates? | Personal plans for more than one completion date or net-proceeds figure. |
| Completion could be delayed | Which income continues, which commitments remain and can your retirement date move? | A plan that identifies deferred or conditional receipts and tests the effect of waiting longer for them. |
| You are approaching retirement | How will pensions, other savings and any continuing business income work together? | An income plan and a clear division of responsibilities between professionals. |
Illustration: £800,000 of expected personal sale receipts less a provisional £160,000 tax allowance and £40,000 of costs leaves £600,000 before debts and spending needs. These are invented cash-flow figures, not a tax calculation or an amount to invest. Deferred proceeds may not be available at completion.
Start with the personal decision: building savings outside the business, preparing for retirement or planning around a sale. Ask how the adviser would coordinate with your accountant or solicitor.
Outline how the business supports your income, your broad timescale and what you want to change. Detailed company accounts are not needed for an Advisedly enquiry.
Check whether the meeting is free and agree the scope and fee before paid work begins. Take the free meeting pack with you, then compare written quotes once you have them.
Advisedly’s enquiry service is free. We review your answers and aim to acknowledge your enquiry within one working day, with an update on the next step within two. You choose whether to take advice.
Look for evidence that the adviser regularly works with owner-managers and understands how business decisions interact with personal wealth. Useful areas to compare include pensions, extracting money from the business, protection, retirement planning, investment management and planning around a future sale or succession.
If a sale is likely to create a major change in your personal finances, it can be useful to work with someone familiar with business exits and post-sale planning. The key point is to find an adviser whose experience matches the complexity of your situation rather than simply choosing the nearest generalist.
Ask for the initial and ongoing costs in pounds as well as percentages, understand whether fees are tiered or capped, and check what service is included. Advisedly keeps confirmed adviser pricing separate from generic fee illustrations.
What business owners should look for in a financial adviser, including founder experience, pensions, protection and personal planning around the company.
Read guide →Why founders may want financial planning before a company sale and what to organise before transaction proceeds arrive.
Read guide →Financial planning after a business sale, including cash, investment risk, retirement, diversification and adviser fees.
Read guide →An irregular income does not prevent long-term planning, but it makes the order and timing of commitments important. A high annual total can hide several months when cash is…
Read guide →A first substantial Self Assessment bill can be larger than expected because the payment date may combine tax for a completed year with an advance payment towards the next…
Read guide →A redundancy package can contain several payments with different tax treatment. The total on a settlement illustration is not necessarily the amount that reaches your bank…
Read guide →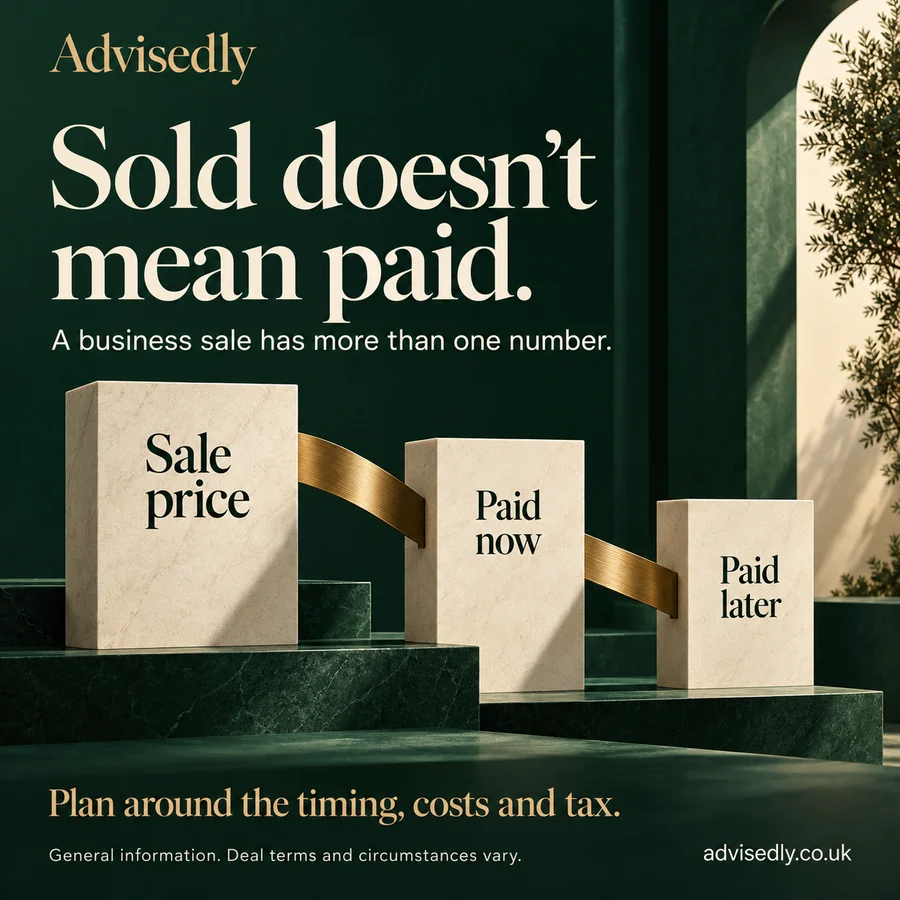
A headline sale price, money paid at completion and payments due later can be different figures. Record the timing and conditions before using sale proceeds in a personal plan. Costs, tax and deal terms also matter.
Prepare for the conversation